The problem
Nobody gives you a list of the documents a pension claim needs. So you gather what you think is right, send it, and wait — and one missing paper is enough to push everything back by months.
Your State Pension isn’t worked out from your payslips. It’s worked out from one National Insurance record, held by HMRC — and years go missing from it quietly: time abroad, years at home with children, a spell self-employed, an employer who never filed properly. Nothing arrives in the post to tell you.
None of this was ever explained to anyone. When most of us started work the payslip said the employer handled it, and for years that was true enough. You didn’t miss anything. Nobody sent it.
Your National Insurance record is on GOV.UK. Most people have never opened it. Look at one number: the qualifying years it shows you. You need 10 to get anything at all, and a full new State Pension is quoted against 35 — though if you were ever contracted out, GOV.UK says you will usually need more than 35. Either way they are years the record counted, which is not always the same as years you worked.
A missing year doesn’t cost you once. It comes off every weekly payment, for as long as you live — and it comes off quietly. Nothing arrives in the post to tell you.
Nobody gives you a list of the documents a pension claim needs. So you gather what you think is right, send it, and wait — and one missing paper is enough to push everything back by months.
“I’ve kept all my payslips, so I’m covered.” Payslips prove you were paid. They don’t prove your National Insurance record is complete — and plenty of records have gaps their owner never hears about.
Your pension is worked out from one record, not from your paperwork. If a year is missing from it, you are paid less for the rest of your life — unless you spot it and say so while it can still be put right.
One weekend, and it’s gathered. What to request, from whom, in what order, and what to check on each thing when it lands — so the claim goes through first time instead of coming back six weeks later.
Your parents were told what they’d get and on what date. That world has largely gone: the choices, and the consequences, now sit with you. Nobody is in charge of pulling your retirement together — not your employer, not the government, not your pension provider. Here’s the gap —
What you are paid comes from your National Insurance record. Payslips, P60s and contracts are how you prove a year that record has got wrong — they are not the record itself.
In the plan: how to read your record, what each document is actually for — and where a document is enough, versus where the year has to be bought back.
Years abroad, years raising children, years self-employed, a change of employer that never filed properly. Nothing arrives in the post to warn you — you have to go and look.
In the plan: the seven places gaps hide, which of them a document can close for free, and which of them cost money to close.
A claim that arrives incomplete doesn’t get refused — it gets held up. Then it’s letters, phone queues and weeks of chasing one document. You don’t lose the money: once the claim is sorted out, what you were owed from your start date is paid as arrears. You just wait for it, at the exact moment you had planned not to have to.
In the plan: the full checklist, so nothing is discovered missing after you’ve sent it.
Nobody checks your record on your behalf. Not your employer, not HMRC, not the DWP. There is no letter, no alert, no annual statement that says a year is missing — the record simply sits there being wrong until somebody looks at it. Putting it off isn’t a character flaw. It’s what happens when something important has no obvious first step.
Three windows, in the order you’ll meet them, each one shorter than the last: six years to put a gap right, four months to claim, two months before the letter is meant to land. Each one tells you what to do while it’s still open — and what closes when it shuts.
A missing year can normally be paid for going back six tax years, and the line moves every 5 April. Since HMRC put the top-up service online in April 2024, 37,000 people have paid to fill 68,673 years between them — £35 million in all, an average of £1,835 each. Two thirds of the years they bought were from 2017 onwards, so this isn't ancient history.
GOV.UK puts it plainly: you will not get your State Pension automatically, you have to claim it. You can ring and claim from four months before you reach State Pension age — you don't have to wait to be invited, and everything you will be asked for should already be in one folder by then.
An invitation letter is meant to reach you about two months before you get there. It is a prompt, not a trigger — it doesn't start anything, and it doesn't always arrive. If you've used the first two windows, it lands on a folder that's already finished.
The order never changes — the plan flags where Scotland, Wales or Northern Ireland differ.
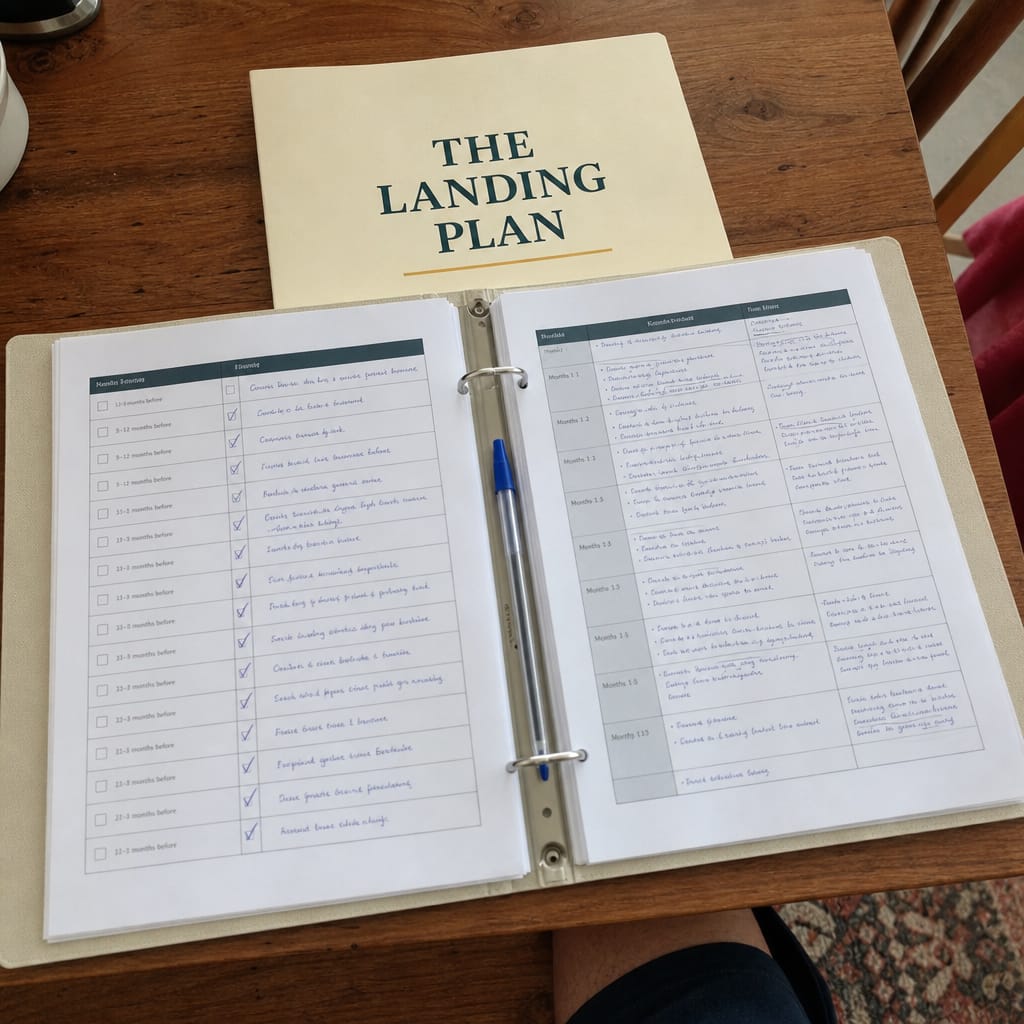
Every section ends with something to write down, tick off or put in the folder — because the difference between the people who sort this and the people who don’t is almost never knowledge. It’s having somewhere to put the answer.
Digital kit, sent by email and printed at home. Nothing is posted.
Guided questions and clear sections — no blank-page overwhelm, no jargon, no financial training required. You fill it in at your own pace, print it, and keep it together.
Not a forecast you half-understood. The years, listed, with the ones that are missing showing up as missing. Most people go their whole working life without ever looking at it once.
A gap found in time is a decision you get to make: correct it with a document if the record got it wrong, buy the year back if it genuinely wasn’t paid, or leave it because the sums don’t work. A gap found afterwards is none of those — it’s a smaller payment, every week, for the rest of your life. The difference is usually just knowing to look while you still have the choice.
Everything asked for is already in one folder, requested in the right order, from the right place. No six-week letter asking for a paper you could have sent on day one.
Not for people who love spreadsheets. For people who want it dealt with, once, on paper.
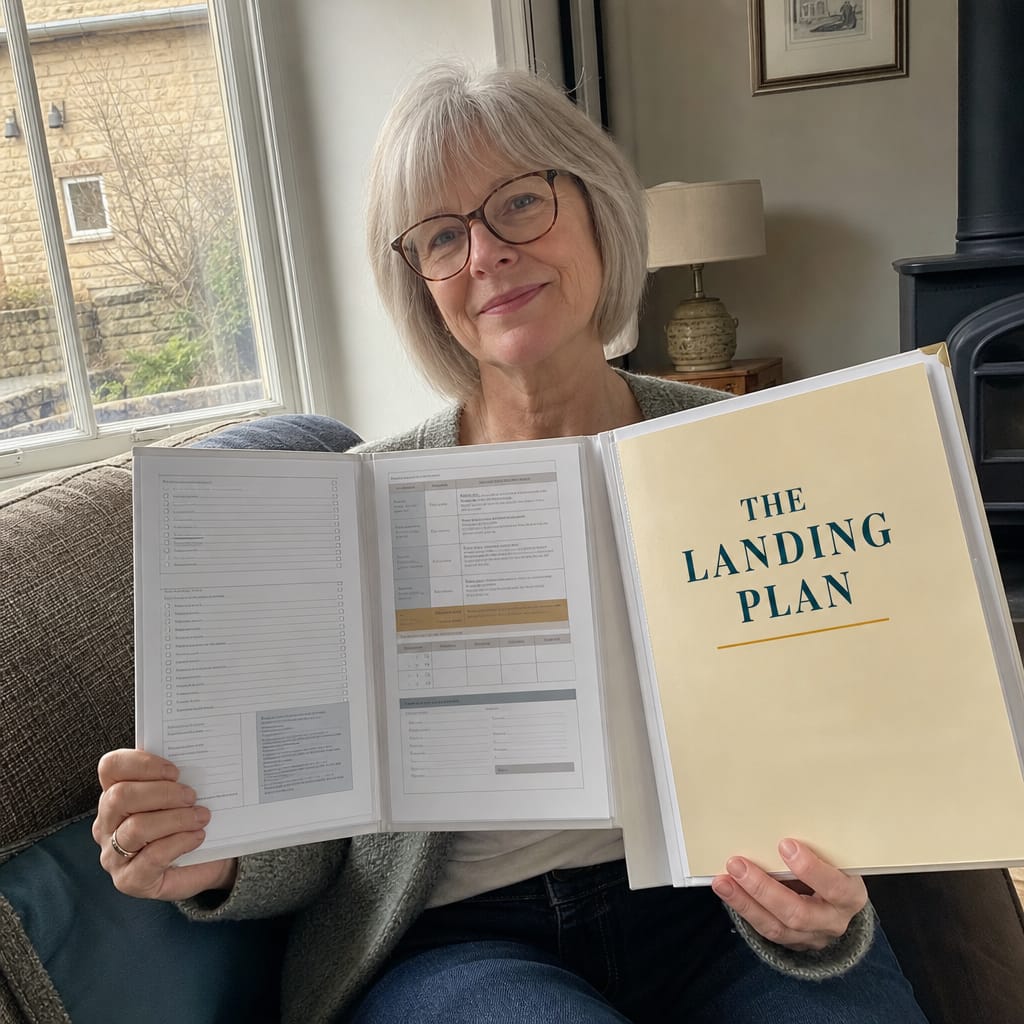
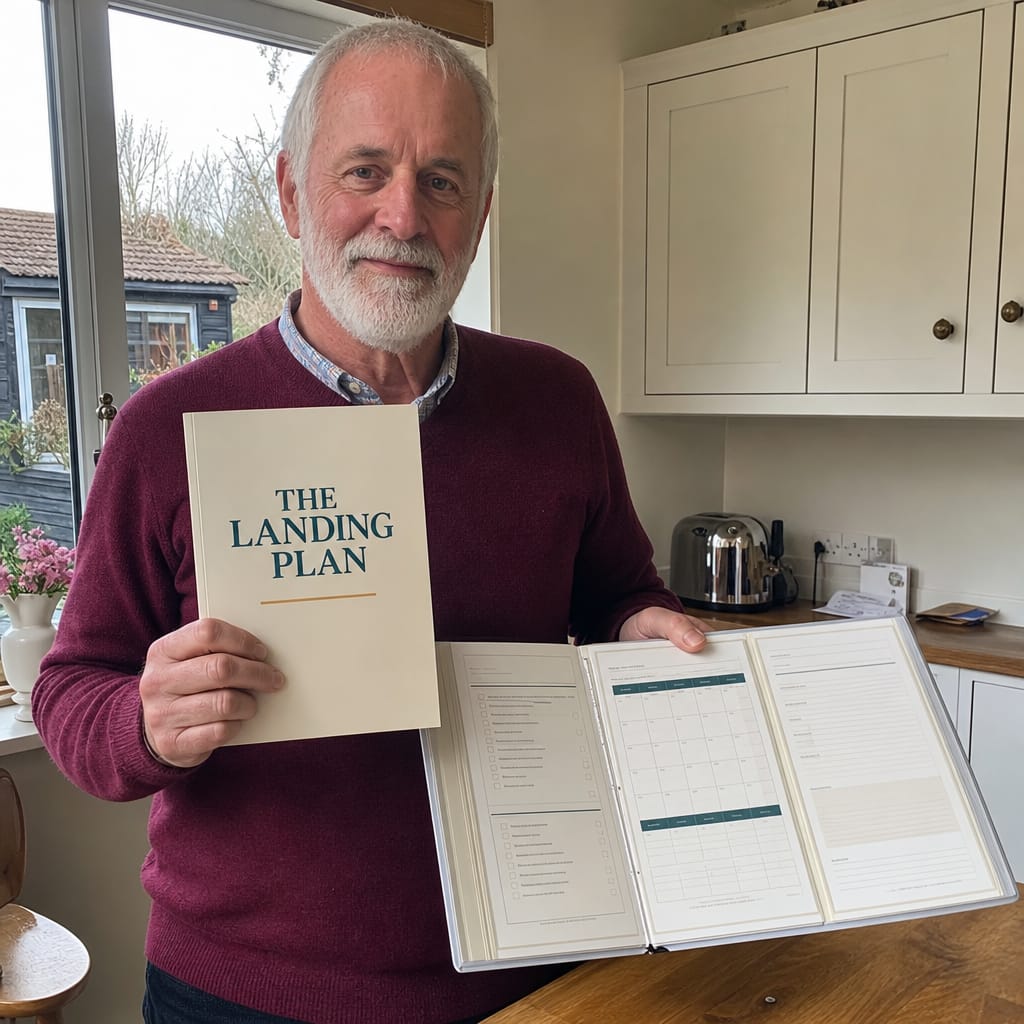
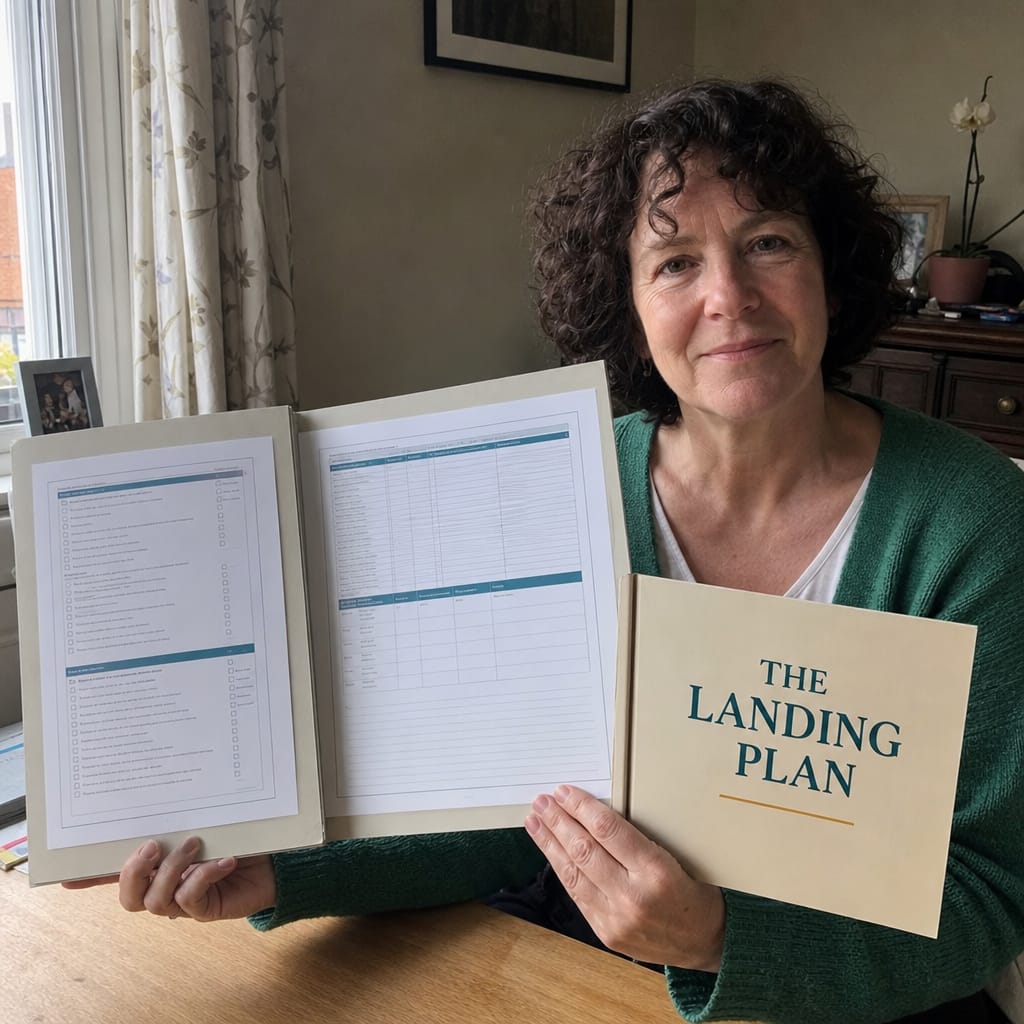
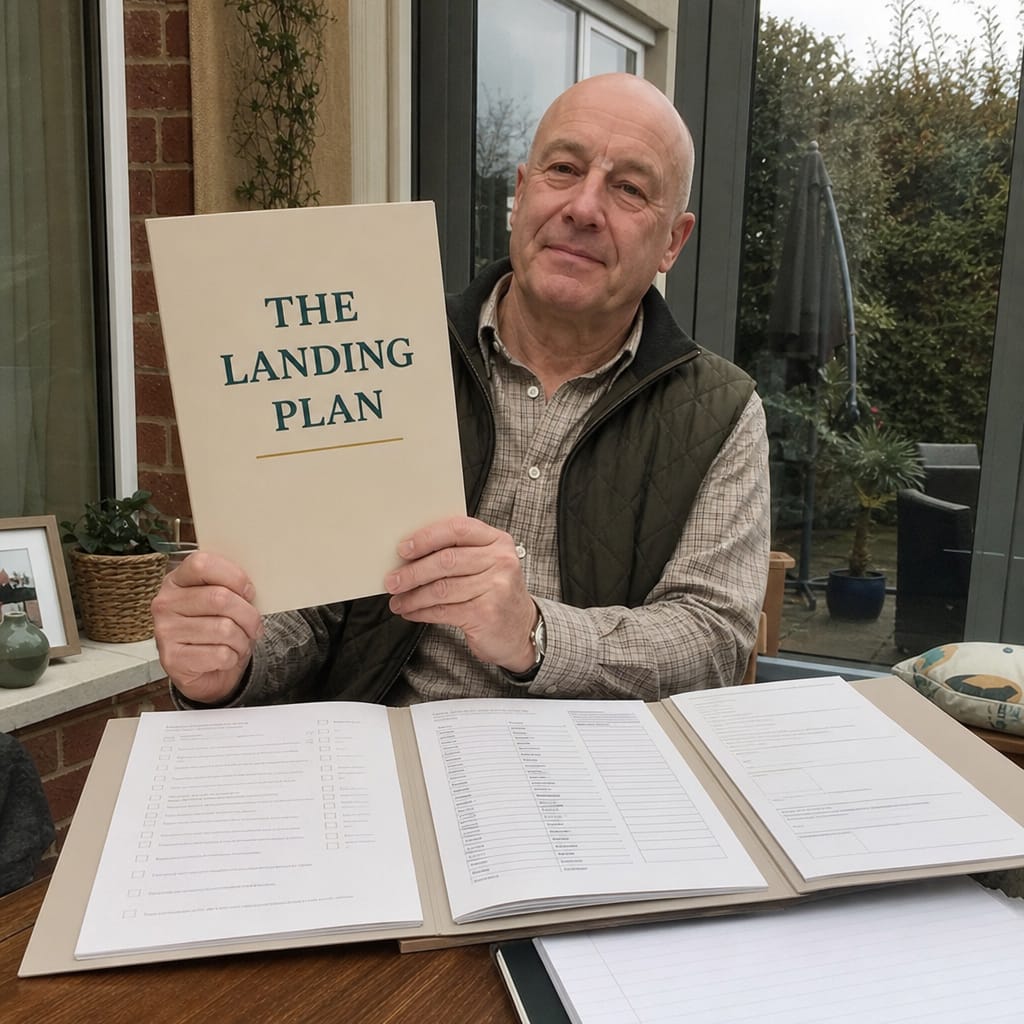
Arrived immediately, I printed it all off very easily. It's well laid out and clear to read, l can now fill it out at my leisure. Very happy to have a job so well organised for me. Thank you.
I liked the layout. Very good idea to read what it all about first before going ahead to fill in or print out pages. The instructions are clear. Just maybe a little too much repetition in some areas but that's better than omission I suppose. When I made a query I got an instant response - excellent service.
So much more to the process than I ever imagined, this kit is a virtual GPS for what to do and when with all angles covered. Highly recommended
The whole family is very glad to have such clear, essential information and advice. Thank you for producing this Kit. It is excellent and very much needed. My one gripe is that you use abbreviations, such as “you're”, “they're”, “that's” and so on, which I find patronising.
I have scanned through the complete Kit and have found it to be very comprehensive. It is a lot to absorb and understand at first glance but your step by step explanation and advise seems to be quite thorough. If I do come across anything that I will need further clarification on I will certainly be getting back in touch with you. Thank you.
This looks a very comprehensive set of guidance/supprt notes and looking forward to going through the process over the next few weeks
A fantastic kit which will give peace of mind to all the family. Extremely well presented and thought out.
Very thorough. Some of the colour printing is very faint.....and considering this is for an elderly person, readability is important.
All three areThe Landing Plan — the same plan, at three depths. Whichever you choose, that is the name you’ll see at checkout and on your receipt. One-off payment, delivered by email to print at home, with a 30-day money-back guarantee.
The Landing Plan · everything requested in one go, in the right order.
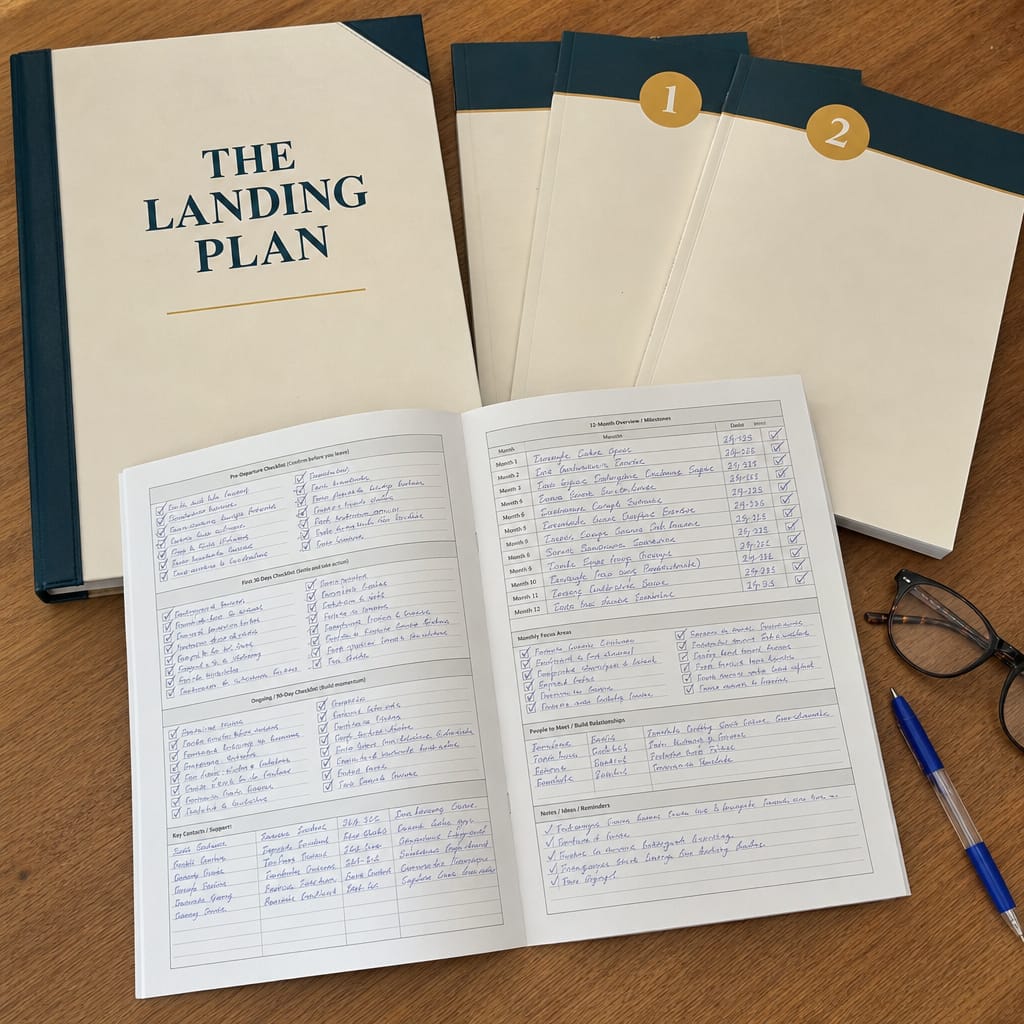
The Landing Plan · proving the years you actually worked.
The Landing Plan · everything requested, checked and filed.
Which one? Open your record on GOV.UK first — it’s free, it takes five minutes, and it tells you which of these you actually need. If the qualifying years come up short, take The Record Check: that is the version that reads the record line by line, names the seven places gaps hide, and gives you the letters. If the years add up— good, that’s the best outcome on this page and it cost you nothing — and if you still want the claim itself gathered and checked in one go, that’sThe Gathering Plan. This isn’t financial advice and doesn’t replace it: it’s the part you can do yourself, in order.
Download the plan, print the sheets and start filling them in at your own pace. If you want your money back, for any reason at all, email raphael@retiresorted.com within 30 days: we refund you in full, no forms and no questions, and you keep the file. That is on top of your legal right to cancel within 14 days under the Consumer Contracts Regulations 2013, which we don’t ask you to waive.
No, and it matters to be clear about that. The Landing Plan is a practical organiser: how to read your own National Insurance record, what each document is for, and the order to request things in. It never tells you which pension product to choose, never recommends a provider, and never suggests what to do with your money. For decisions about your own pension, speak to Pension Wise — free, impartial and government-backed — or to a regulated financial adviser.
The services are free, they're good, and we point you to every one of them — starting with your own record, which you should look at tonight whether or not you buy anything. What none of them does is tell you which document proves which year, who to write to when a year is wrong, or what a claim will ask you for. That list, that order, and the wording — that's what you're paying for.
Then you'll know that before you spend anything, which is the point. There are two sorts of gap. Where the record simply got it wrong — credits for years at home with children that were never applied, an employer who deducted contributions and never filed them — a document and a letter put it right, and that costs you nothing. Where a year genuinely wasn't paid, because you were abroad or self-employed under the threshold, the only way to close it is to buy it back, and a year currently runs to several hundred pounds. HMRC's own figures put the average online top-up at £1,835. Sometimes that pays for itself many times over and sometimes it doesn't — it depends on how many years you already have and how long you live. The plan shows you which sort you're looking at and how to work the sum out. It does not, and cannot, make a paid year free.
The opposite. A missing year can normally only be paid for going back six tax years, and that line moves every 5 April. The earlier you look, the more of your record is still within reach. Looking costs you five minutes and nothing at all.
Not necessarily. Records get corrected after a claim as well as before, and the six-year window for paying voluntary contributions doesn't close just because you've claimed. If a year is wrong, it's worth knowing — it comes off every payment from here on.
A set of printable documents, sent to the email address you use at checkout. Your receipt and the link to your file both arrive straight away — nothing to wait for and nothing is posted. Read them on screen, or download the A4 PDF of each one and print it at home. They're made to be worked through with a pen. No app, no login, no subscription.
Yes. The State Pension and National Insurance work to the same rules across England, Scotland, Wales and Northern Ireland — one kit, no regional small print on the rules themselves. The one practical difference is who you deal with: in Northern Ireland the claim goes to the Northern Ireland Pension Centre rather than the Pension Service, on a different number and a different address. Both are in the kit, side by side.
Yes. Payment is handled by Stripe or PayPal — we never see or store your card details. You'll get an email receipt immediately.
Email us within 30 days and we refund you in full, for any reason at all — no forms and no questions — and you keep the file. That is on top of your legal right to cancel within 14 days under the Consumer Contracts Regulations 2013, which we don't ask you to waive.
One-off payment · sent by email · 30-day money-back